Tech Carnage Continues, With Anthropic Now Falling
Published as of: November 20, 2026, 9:16 a.m. ET
Listen to this article
Listen here or subscribe to the Schwab Market Update in your favorite podcast app.
| The markets | Last price | Change | % change |
|---|---|---|---|
| S&P 500® Index | 7,175.83 | -147.80 | -2.02% |
| Dow Jones Industrial Average® | 49,097.06 | -1,101.11 | -2.19% |
| Nasdaq Composite® | 23,879.19 | -550.68 | -2.25% |
| 10-year Treasury yield | 4.96% | -0.08 | -- |
| U.S. Dollar Index | 103.63 | -0.25 | -0.25% |
| Cboe Volatility Index® | 31.30 | +2.86 | +10.06 |
| Gold | $3,558.00 | -$127.30 | -3.46% |
| WTI Crude Oil | $82.33 | -$0.11 | -0.13% |
| Bitcoin | $61,430 | -$610 | -0.98% |
(Friday market open) Stocks stumbled into the weekend, under pressure again thanks to a 10% early plunge for Anthropic (ANT) after its successful initial public offering yesterday. Nvidia (NVDA) lost ground, too, extending a tech plunge that's made this Wall Street's worst week since the April 2025 tariff sell-off. The S&P 500 Index is down six straight sessions, off 5% from last Friday's close.
Next week is shortened by Thanksgiving, though investors will navigate a data thicket as they head over the river and through the woods. Before that, investors await today's 10 a.m. ET final November University of Michigan Consumer Sentiment report, which offers inflation expectations ahead of potential rate hikes. But the main concern is AI, with the PHLX Semiconductor Index (SOX) down almost 30% from recent peaks and leaving investors wondering where the market might go if its engine keeps losing steam.
On Thursday, major indexes cratered despite Anthropic's 17% rise. The S&P 500 Index finished at six-month lows. "Although we are near-term oversold in the AI cohort, the price action still has a bearish feel," said Nathan Peterson, director of derivatives research and strategy at the Schwab Center for Financial Research (SCFR). "Investors are selling into any rallies, rather than buying the pullbacks."
To get the Schwab Market Update in your inbox every morning, subscribe on Schwab.com.
Three things to watch
- Sentiment gloomy amid AI regulation concerns: A hot start yesterday quickly cooled. This has been a feature lately, not a bug. The bleak mood began last summer when some U.S. states toughened data center approvals. Texas said Wednesday it would again start approving data centers. But the Nvidia controversy occurred at an auspicious juncture after the "blue wave" election, and the SOX remains very unsteady, falling 400 points out of the gate Thursday. "More broadly, the Nvidia situation is causing a rethink of things like export controls on chip sales—the very thing that Jensen Huang has been advocating against over the last year or more," said Michael Townsend, managing director, legal and regulatory affairs at Schwab. "China policy generally is likely to get tougher when Democrats take office in January." Democrats might work with President Trump to put guardrails in place on AI, Townsend said. These could include "kill switches" and government vetting of new models prior to release.
- Recent pressure also reflects rates: Surging October jobs and inflation has investors anticipating a more aggressive path for rates, a sure way to sap enthusiasm on Wall Street. By next June, the market expects the Federal Reserve's target range to be 50 to 75 basis points higher than today's 3.75% to 4%, according to the CME FedWatch Tool. In some ways, the Fed's tightening bias and the AI buildout are linked in a bearish knot. "Recent hawkish Fed speak is not helping sentiment, given the concerns around longer-term AI financing to fund the buildout," Peterson said. "So, although there has been a significant sell-off in the AI complex, along with a meaningful spike in the VIX, I'm not sure we have hit 'capitulation' yet given the price behavior." The Cboe Volatility Index (VIX), known as the "fear index," rose another 10% today to above 31, near the March high. Anything higher than 20 traditionally represents rising uncertainty. This can drive investors to seek perceived "safety" away from stocks, and there's evidence of that, too, with the dollar at 19-month highs and Treasury yields falling to one-week lows this morning.
- "Mind the gap" moment, technically: The S&P 500 Index's descent below its 200-day moving average of 7,340 to lows last seen in April put traders on the edge of a deep technical gap on the charts. Earlier this year, the index went on a tear, roaring from its late March low near 6,300 to highs of 7,600 by early June, a 20% gain in just two months. That leaves a lot of room below current levels if the index can't collect itself here after its 6% drop since the November 3 U.S. election and its worst performance since early last year. The next technical support for the SPX is probably near 7,000, and the Dow Jones Industrial Average is approaching correction territory, down almost 10% from highs. In another sign of the carnage, 58% of the components of the tech-heavy Nasdaq-100® (NDX) are in a bear market, down 20% or more.
On the move
- Anthropic initially tumbled almost 10% early after its strong start Thursday in which it gained 17% from its IPO price. Shares appear caught up in general AI and risk-off selling. The rally yesterday compared to a 19% gain on the first day of trading for SpaceX (SPCX) earlier this year.
- Nvidia fell almost 3% ahead of the open. U.S. lawmakers are probing the influence Nvidia has over a U.S. Commerce Department investigation into Megaspeed for possibly obtaining chips for China, Reuters reported.
- Nvidia competitor Advanced Micro Devices (AMD) toppled 6% early today. Reuters reported on allegations that the company's ties with Chinese entities could attract more U.S. regulatory attention, which AMD denied in the Reuters article.
- Chip and AI-related stocks, which fell almost across the board in yesterday's sell-off, didn't fare much better early. Some of the worst performers included Sandisk (SNDK) down almost 7%, Taiwan Semiconductor Manufacturing (TSM) off almost 6%, and SpaceX down 6%. TSM and Samsung suspended some chip sales to Chinese customers, the Financial Times reported.
- AI-adjacent names including Dell (DELL) and Bloom Energy (BE) were sharply lower this morning, down 6% and 8%, respectively. Caterpillar (CAT) fell 3.4% and hit new lows for the year yesterday, down 50% from the summer peak as AI data center demand worries spike.
- Intuit (INTU) plunged 9% early despite earnings and revenue topping expectations. Guidance was below analysts' thinking for the financial technology firm.
- One strong area early was retail, with American Eagle Outfitters (AEO) up nearly 5% and Gap (GAP) up 3.5%. Gap earnings beat analysts' expectations, though comparable sales were flat annually and the company lowered guidance. Strength in the Old Navy category helped shares, Reuters reported. Ross Stores (ROST), however, fell 5% on below-consensus guidance.
- Health care stocks, especially managed care and insurance companies, rebounded slightly this morning. They fell sharply Thursday amid concerns over a possible legislative push toward a Medicare For All model.
- Gold continued sinking, down another 2.9% early and dropping to a 14-month low below $3,600 an ounce as investors fretted over recent hawkish Fed comments.
- Market breadth deteriorated Thursday. Just 49% of S&P 500 stocks traded above their 200-day moving average.
- Crude is down 7% this week to nearly three-month lows, partly on rising U.S. stockpiles but also possibly due to seasonal weakness. This might help ease the November Consumer Price Index (CPI) reading.
More insights from Schwab
AI momentum in question: Today's Schwab On Investing podcast addresses a question on many investors' minds: Is the AI trade losing momentum? The episode points out how much next year's S&P earnings growth depends on a handful of AI-related stocks, including Nvidia and Micron (MU). The podcast also looks at next week's market schedule and analyzes the latest remarks from Fed policymakers.
TAM considerations: Total Addressable Market (TAM) is a company's estimate of the total dollar value of the market for its products, and it often appears in IPO prospectuses. The SpaceX TAM was $28.5 trillion, but that shouldn't be confused with expected revenue. Learn more about TAM and other ways to value a new company in our latest look at IPOs.
Concentration risk management: Stock market concentration remains near 35-year highs, meaning a few mega-cap stocks form about 39% of the S&P 500 Index. Concentration can magnify losses if market leadership shifts, meaning it might be time to consider diversification. Our new analysis discusses three ways to manage concentration risk.
Chart of the day
Data source: Nasdaq. Chart source: thinkorswim® platform.
Past performance is no guarantee of future results.
For illustrative purposes only.
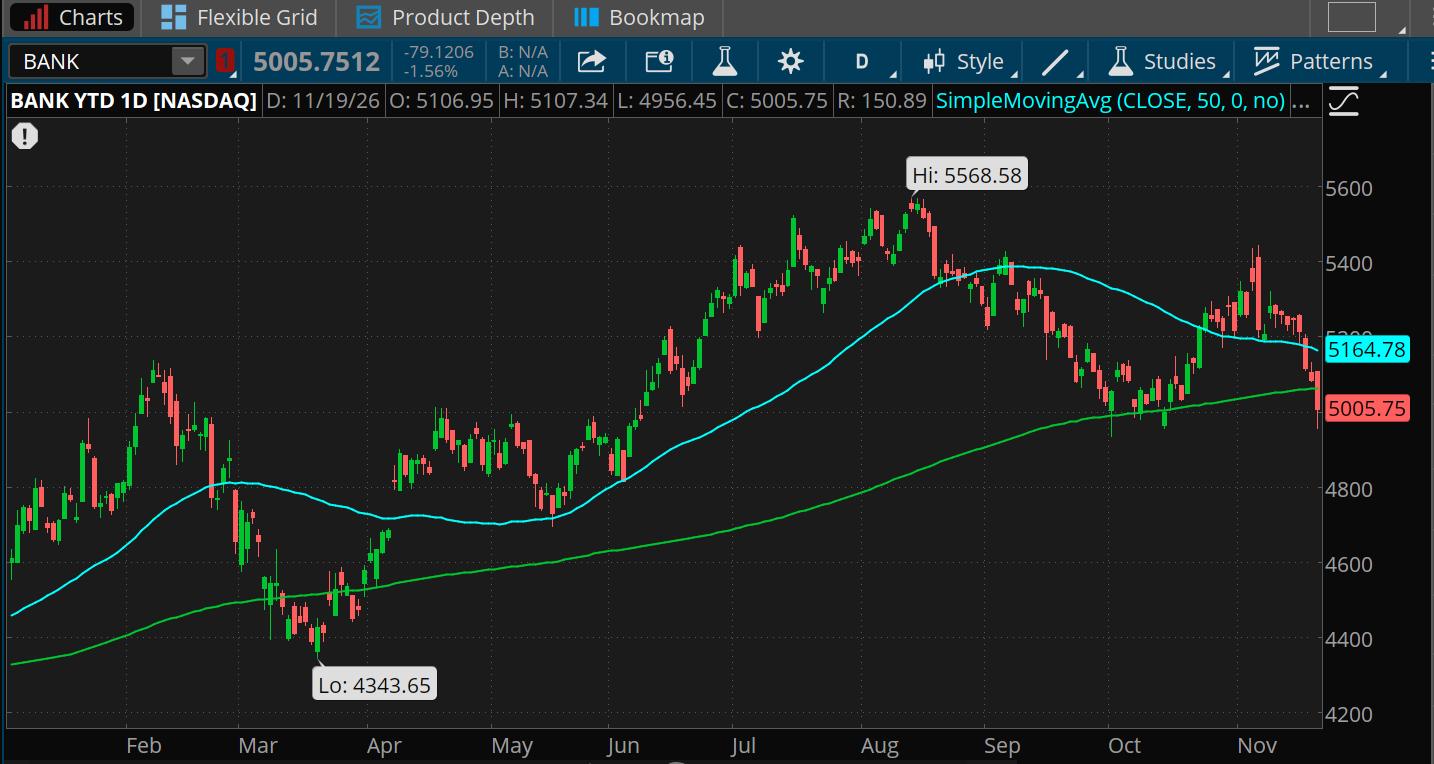
The Nasdaq Bank Index (BANK—candlestick) is in correction mode, down 10% from its mid-August peak. Banks face increased pressure from the recent technology-related business disruptions and higher borrowing costs as the Fed considers more rate hikes. The index has dropped under both its 50- and 200-day moving averages (blue and green lines, respectively). If the descent continues, it could set up a rare "death cross," a bearish technical chart pattern where the 50-day crosses below the 200-day. That already happened yesterday for the KBW Bank Index.
The week ahead
Friday, November 20: University of Michigan final November Consumer Sentiment and expected morning earnings from BJ's Wholesale Club (BJ).
Monday, November 23: Expected afternoon earnings from Hewlett Packard Enterprise (HPE) and Zoom Communications (ZM).
Tuesday, November 24: November Consumer Confidence and expected morning earnings from Analog Devices (ADI), Medtronic (MDT), Dollar Tree (DLTR), Best Buy (BBY), Burlington Stores (BURL), and Dick's Sporting Goods (DKS). Expected afternoon earnings from Dell (DELL), Autodesk (ADSK), Workday (WDAY), HP (HPQ), and Urban Outfitters (URBN).
Wednesday, November 25: October durable goods orders, third-quarter GDP second estimate, October PCE prices, October new home sales, Fed Beige Book, and expected morning earnings from Deere (DE).
Thursday, November 26: U.S. markets closed for Thanksgiving.
Friday, November 27: No major earnings or data, stocks close early at 1 p.m. ET.