Sector Views: Monthly Stock Sector Outlook

Schwab Sector Views is our six- to 12-month outlook for stock sectors, which represent broad sectors of the economy. The Schwab Center for Financial Research (SCFR) combines a factor-based approach with a market and economic assessment to determine the ratings. For the basics on sectors, please see Stock Sectors: What Are They? How Are They Used?
There are no changes to the Schwab Sector Views from last month. Last month, we upgraded Energy from Neutral to More Favored, and downgraded Communication Services from Neutral to Less Favored.
So far, our views are in line with how these two sectors have actually been performing. Energy was the S&P 500's best-performing sector in October, due in part to high oil prices, which continue to remain elevated. Communication Services was the worst-performing sector, due in part to heavy investment spending and an unpredictable return on investment (ROI) that could be creating uncertainty.
Sector ratings
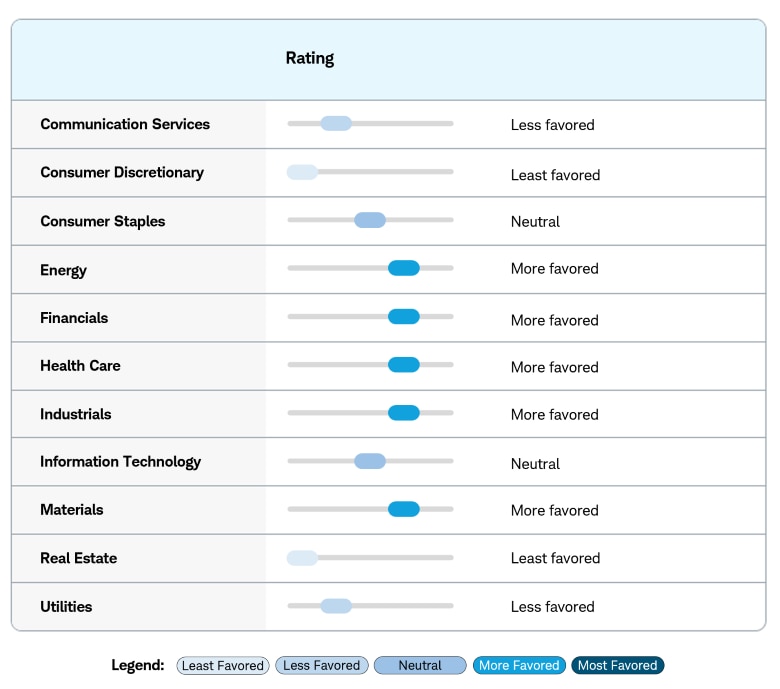
Source: Schwab Center for Financial Research, as of 10/30/2026.
The ratings Most Favored, More Favored, Neutral, Less Favored, and Least Favored reflect SCFR's opinions about the likelihood that the sector will perform better (Most Favored, More Favored), about the same (Neutral), or worse (Less Favored, Least Favored) than the broader S&P 500® index during the next six to 12 months. Sectors are based on the Global Industry Classification Standard (GICS®), an industry analysis framework developed by MSCI and S&P Dow Jones Indices to provide investors with consistent industry definitions. This material is intended for general informational and educational purposes only. This should not be considered an individualized recommendation or personalized investment advice. Investing involves risk, including loss of principal.
Sector performance and concentration statistics
| Sectors (in alphabetical order) |
Weighting in S&P 500 (%) |
Trailing six-month performance (%) | Trailing 12-month performance (%) | Weight of 3 largest stocks (%) | Weight of 10 largest stocks (%) |
|---|---|---|---|---|---|
| Communication Services | 9.9 | -8.1 | 2.6 | 80.0 | 96.9 |
| Consumer Discretionary | 8.6 | -4.6 | -2.0 | 65.1 | 79.6 |
| Consumer Staples | 4.4 | 6.2 | 14.8 | 42.2 | 79.7 |
| Energy | 3.4 | 24.1 | 62.6 | 55.2 | 82.2 |
| Financials | 11.4 | 9.5 | 7.0 | 32.9 | 57.3 |
| Health Care | 9.3 | 25.4 | 24.9 | 33.3 | 60.5 |
| Industrials | 8.0 | -4.1 | 7.6 | 16.6 | 37.7 |
| Information Technology | 39.7 | 12.6 | 19.7 | 56.6 | 76.6 |
| Materials | 1.7 | -0.8 | 16.5 | 39.9 | 75.9 |
| Real Estate | 1.7 | -1.1 | 4.7 | 33.3 | 68.9 |
| Utilities | 1.9 | -6.5 | -4.1 | 28.1 | 58.8 |
| S&P 500 index performance for the trailing six or 12 months (%) | 7.0 | 13.6 |
Stock sector commentary
(Sectors are listed in alphabetical order)
Communication Services sector (rating: Less Favored)
Positives: Growth in digital advertising, data consumption, and streaming services continues to support the sector. Steady carrier activity and 5G deployments continue—with likely future upside from Artificial Intelligence (AI)-enabled networks—which may create additional demand. Search, social, and content platforms may increasingly monetize AI tools.
Risks: Communication Services has a high exposure to advertising revenue, which can weaken during periods of economic slowdown. The sector is also exposed to competitive pressures in more mature markets like telecommunications and media. Heavy AI spending may take time to produce the earnings investors expect, and new AI agents could affect advertising economics. The sector continues to be highly concentrated in a few individual stocks, with nearly 80% of the sector's weight attributed to just three stocks, raising idiosyncratic risk. Price momentum has weakened recently and some companies in the sector are exposed to elevated debt or regulatory pressures.
Consumer Discretionary sector (rating: Least Favored)
Positives: Structural trends in e-commerce and digital transformation continue to support long-term growth. The sector has benefited from economic expansion and rising consumer spending. Affluent consumers continue to support discretionary categories, with Hotels and Leisure within the sector showing strong earnings momentum.
Risks: The sector is highly exposed to economic conditions and thus vulnerable to a slowing economy and reduced consumer confidence and spending. Tariffs and inflation could affect companies' profitability and consumers' discretionary spending. Concentration risk is also high for the sector, as approximately 65% of its weight comes from three stocks. While higher-income customers continue to spend, excess savings have evaporated for most U.S. consumers, leading to challenged pricing power for retailers. High operating leverage across most subsectors means downside risks are amplified.
Consumer Staples sector (rating: Neutral)
Positives: Consumer Staples is relatively insensitive to economic cycles as demand for everyday items tends to be steady during economic downturns. The sector's valuation remains attractive relative to the broader market, and it has a low correlation to stocks directly tied to the AI capital expenditure (CAPEX) cycle. In a higher-yield environment, Consumer Staples' dividend yields tend to remain competitive.
Risks: The sector offers limited growth potential compared to cyclical sectors during economic expansion and is highly competitive, which can affect profitability. Higher commodity, transportation, and packaging costs may force companies to raise prices just as consumers become more cost conscious, which could reduce sales volume. Many of these companies face meaningful foreign exchange and geopolitical risks, which may be amplified at this time, potentially increasing the headwinds the sector is facing.
Energy sector (rating: More Favored)
Positives: Energy stocks are generally supported by high oil prices, which have been a factor in the current geopolitical climate and Middle East conflict. The sector has attractive valuation characteristics, and the long-term need for a reliable energy supply continues to encourage investment in production and infrastructure. Strong near-term demand and growing interest in liquified natural gas may benefit select companies.
Risks: The sector is vulnerable to regulatory changes and policy shifts toward renewable energy and decarbonization. While geopolitical risk can support oil prices, it can also cause supply disruptions and price controls that can be disruptive to earnings. Strong U.S. oil production has weighed on oil prices in recent years and prices could revert lower if geopolitical stress in the Middle East fades. This group is highly concentrated, with the largest three stocks making up over half of the sector's weight. The near-term outlook is heavily dependent on the trajectory of U.S.-Iran hostilities, which could potentially escalate after midterm elections.
Financials sector (rating: More Favored)
Positives: Higher interest rates and a steeper yield curve can support bank lending margins and insurers' investment income. Structural trends in digitalization and financial technology are creating new revenue opportunities. Stronger fundamental conditions have resulted in improved earnings estimates and dividend capacity, while capital markets activity remains constructive across underwriting, advisory, trading, and debt issuance. A resilient labor market and healthy corporate balance sheets tend to support lenders, and the sector continues to trade at lower valuations than the broader market. Current earnings revisions, net interest income, and capital markets trends may provide a favorable backdrop for the group.
Risks: Financials are highly sensitive to interest rate changes and central bank policy decisions. Interest rate cuts were more widely expected at the start of 2026, but in September the Federal Reserve increased rates and signaled potential future increases. Keep an eye on December's Fed meeting, because according to Bloomberg, the odds of a hike on December 9 are over 80%, as of October 27, 2026. Cyclical exposure to economic downturns can impact loan quality and credit losses. Financial tightening due to persistently high interest rates and heightened bank risk controls can weigh on growth. The rapid rise in private credit markets and associated products could cause broader financial-system stress.
Health Care sector (rating: More Favored)
Positives: Health Care is structurally supported by increasing health awareness, technological innovation, and demographic trends, such as an aging population. GLP-1 medicines remain a multi-year secular growth theme, and drugmakers continue to invest in obesity treatments and other promising areas of research. The sector's defensive characteristics may also help during periods of economic uncertainty.
Risks: Regulatory uncertainty includes potential changes to Affordable Care Act subsidies, Medicaid cuts, tariffs, and pharmaceutical pricing. Subindustries that tend to have weaker fundamentals and are more volatile (like biotechnology) can reduce the attractiveness of the sector. Higher medical costs and insurance deductibles may cause some customers to delay care.
Industrials sector (rating: More Favored)
Positives: Industrial demand remains broad-based, driven by AI-related data center construction, electricity-capacity investment, higher defense spending, and energy infrastructure. The growth outlook is structurally stronger than in the previous decade, supported by decarbonization, electrification, digitalization, automation, and re-industrialization. Manufacturing activity has shown signs of broadening, with opportunities across aerospace, transportation, electrical equipment, and construction. Global security concerns continue to support defense budgets, while grid modernization and rising power demand are expanding the opportunity set for engineering and equipment companies.
Risks: The sector has high cyclical exposure to economic downturns. Core end-markets, including Residential and Commercial & Industrial, are highly sensitive to macroeconomic factors like interest rates, housing starts, and investment cycles. Industrials may underperform if tariffs eventually start to eat into profit margins and the manufacturing sector's recovery takes longer than expected. Airlines are vulnerable to elevated fuel prices. Industrials are trading near the upper end of their historical valuation range, so a slowdown in orders, or a delayed manufacturing recovery, could weigh on performance.
Information Technology sector (rating: Neutral)
Positives: The sector's fundamental growth is being supported by strong secular growth drivers, including AI, cloud computing, cybersecurity, automation, and digital transformation initiatives. AI-related CAPEX remains a significant source of demand for semiconductors, networking equipment, and data center infrastructure, while enterprise software vendors are increasingly focused on productivity-enhancing AI applications. Companies with strong balance sheets, recurring revenue models, and leadership positions in critical technology ecosystems continue to generate attractive earnings growth and free cash flow. Demand for electrification, advanced manufacturing, and autonomous systems also supports long-term growth opportunities across several technology industries.
Risks: Elevated valuations and investor expectations have increased sensitivity to earnings disappointments. Many areas of the sector remain dependent on continued AI spending and successful commercialization of new technologies. Enterprise technology budgets could come under pressure if economic growth slows or financing conditions tighten. Regulatory scrutiny, antitrust concerns, and export restrictions affecting advanced technologies remain ongoing uncertainties. The sector also remains highly concentrated, which can amplify volatility should leadership narrow or sentiment shift.
Materials sector (rating: More Favored)
Positives: The Materials sector is seeing structural demand from infrastructure spending, reshoring, and industrialization trends. A recovery in global manufacturing could be supportive for Chemicals and Basic Resources, while exposure to data center expansion could drive demand for specialty materials. Tight supplies and low inventories may benefit copper and other metals. The sector can also outperform during periods of high inflation.
Risks: Materials is a highly cyclical sector with earnings closely tied to global economic growth and industrial production. Commodity price volatility can create earnings unpredictability and margin pressure while trade policy shifts, tariffs, and supply-chain disruptions add to vulnerabilities. Gold faces a headwind with increased rates, while softer activity in China could weigh on construction activity and industrial metals demand.
Real Estate sector (rating: Least Favored)
Positives: Real Estate, which consists primarily of commercial real estate investment trusts (REITs), tends to benefit from economic growth, which supports rent collections and property prices. REITs are favored as defensive sectors typically offering earnings resilience during periods of macroeconomic uncertainty. Structural housing affordability and supply constraints can support the long-term case for renting. Health care properties, data centers, and communication towers are growth drivers that are less tied to traditional real estate. The sector would likely benefit if interest rates stabilize or decline, as lower rates can tend to improve valuations and financing conditions.
Risks: Real Estate is a rate-sensitive sector highly vulnerable to interest rate increases and financing cost pressures. Most REITs borrow heavily, making them vulnerable to elevated interest rates. The sector faces structural headwinds in office and traditional retail segments, and some business models can be disrupted by AI technologies. Although valuations are somewhat attractive, elevated financing costs remain a deterrent.
Utilities sector (rating: Less Favored)
Positives: Domestic-focused power infrastructure and solar players can benefit from structural growth drivers like AI data center expansion, industrial expansion, and the energy transition. The Utilities sector has non-cyclical demand characteristics providing defensive positioning during economic uncertainty. Battery storage, gas generation, and grid upgrades may create additional growth opportunities.
Risks: The sector faces regulatory risks affecting rate approvals and return on investment. Utilities generally has higher financing needs due to capital-intensive infrastructure projects and is sensitive to interest rates that impact the cost of capital for long-term investments. Local concerns about data center power and water use could delay new infrastructure.
How should I use Schwab Sector Views?
Investors should generally be well-diversified across all stock market sectors. You can use the S&P 500 allocations to each sector, listed in the Sector Performance chart above, as a guideline.
Investors who want to make tactical shifts in their portfolios can use Schwab Sector Views ratings as a resource. These ratings can be helpful in evaluating and monitoring the domestic equity portion of a portfolio. These favorability views are our preferences for investment assets relative to their peers shown in each section. The views reflect a six- to 12-month outlook and may change as markets evolve. Views do not guarantee future returns and are not a forecast that an asset will rise or fall. They are not a recommendation. An unfavorable view does not mean the investment should be avoided, nor does a favorable view mean the asset must be included in a portfolio. An asset can be held for diversification, income needs, risk control, tax constraints, etc. We suggest using these views as a guide, incorporating the accompanying rationale and other insights.
The views are positioned across a five-point spectrum: Least Favored, Less Favored, Neutral, More Favored, and Most Favored. The Schwab Center for Financial Research (SCFR) sets these views. The team employs a robust, data-driven approach to guide investors managing cross-asset positions in a globally diversified portfolio. The investment approach incorporates a wide range of quantitative data and qualitative inputs that assess the current market environment relative to historical context.
Schwab clients can log into their accounts and use Schwab's Portfolio Checkup tool to help assess their sector allocations. If they decide to make adjustments, they can use the Stock Screener to research particular sectors. Schwab's ETF Screener and Mutual Fund Screener also can help identify funds that specialize in particular sectors. Before considering any fund, you should consult the fund's prospectus to understand its investment objectives, risks, charges, and expenses. Investors and clients should consider sectors as only a single factor in making their investment decision while considering the current market environment.